Non-Resident Mortgages
Access exclusive banking channels typically offering 60–70% LTV for international buyers. We streamline the mortgage for non-residents approval process and lock in the best mortgage rates in Spain.
Unlock the full potential of your capital. We secure premium financing terms for international buyers and provide comprehensive insurance to protect your assets.
We bypass the retail banking desk. Our institutional relationships with top Spanish banks mean faster approvals, better rates, and bespoke financing structures tailored specifically to affluent investors.
Navigating foreign financing and asset protection requires established relationships. If you are wondering how to get a mortgage in Spain for foreigners, we remove the guesswork. We act as your dedicated broker, securing optimal financing, managing currency exchange, and arranging comprehensive property insurance Spain to safeguard your investment.
Access exclusive banking channels typically offering 60–70% LTV for international buyers. We streamline the mortgage for non-residents approval process and lock in the best mortgage rates in Spain.
Structuring capital for “value-add” flips and portfolio expansions, keeping your liquidity intact while maximizing your investment reach.
High-level coverage for premium homes, rental properties, and construction projects. We seamlessly arrange top-tier home and property insurance in Spain, ensuring total peace of mind from the moment you take the keys.
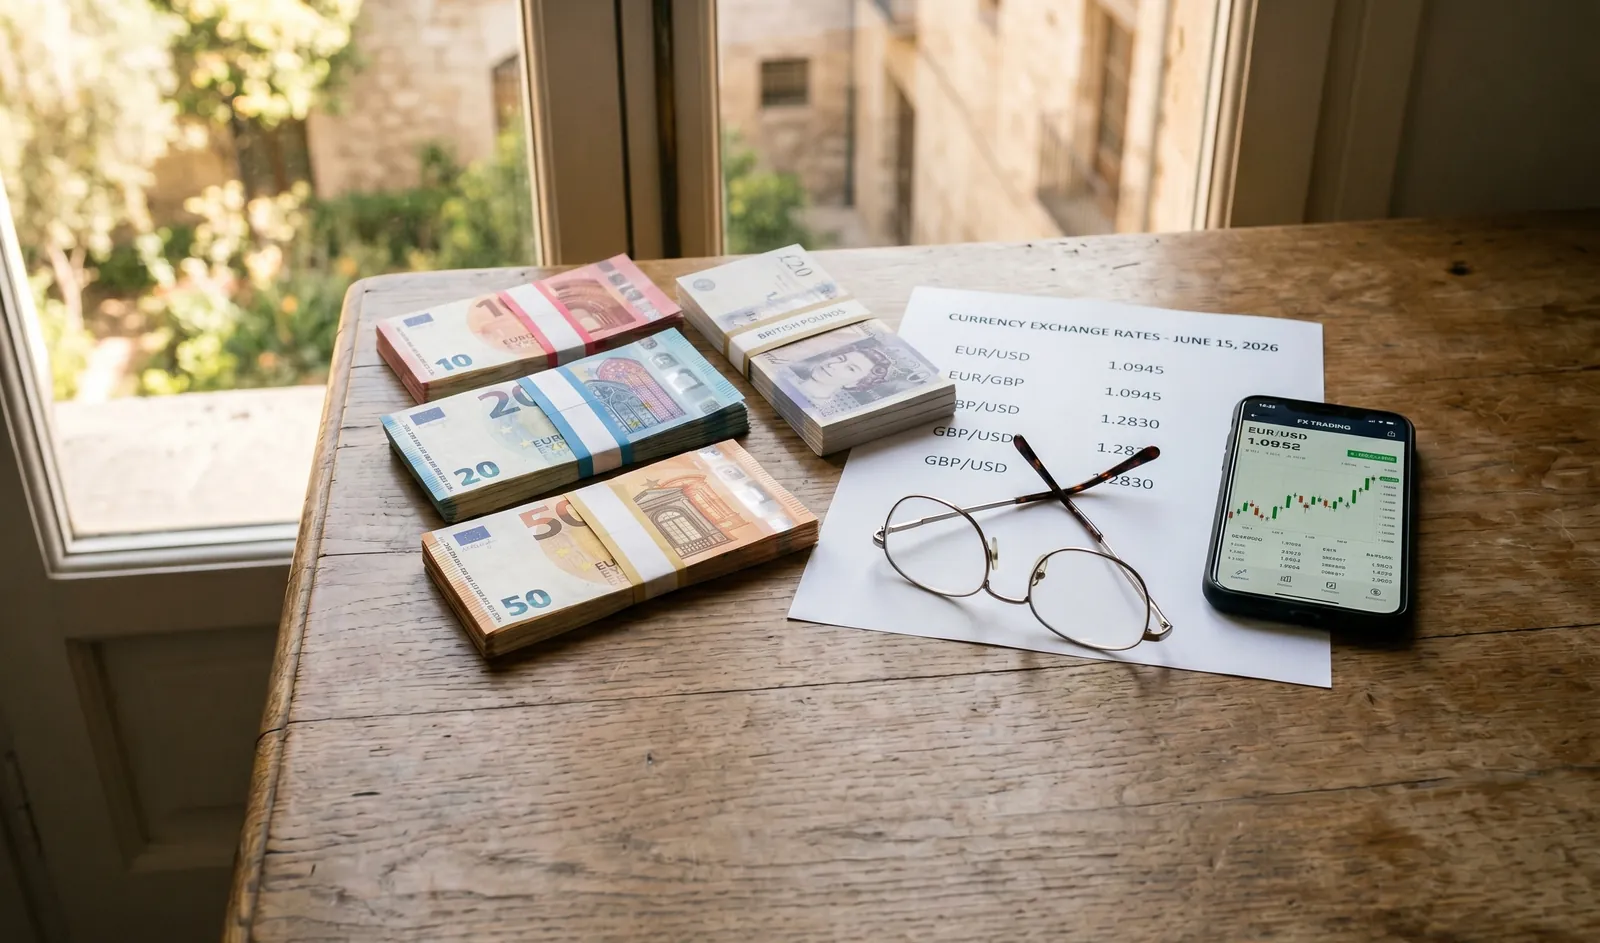
We manage the opening of Spanish bank accounts and acquisition of your mandatory Foreigner Identity Number (NIE). Additionally, our strategic FX partnerships protect your capital from currency fluctuations during large transfers.
Yes. Spanish banks typically lend non-residents up to 60–70% of the property's value (versus up to 80% for residents), so plan for a 30–40% deposit. Income earned abroad is accepted – lenders underwrite on your home-country income and tax returns. SFERO introduces you to banks that actively finance foreign buyers.
As of mid-2026, fixed rates for strong non-resident profiles sit around 3–4%, while variable rates are Euribor plus roughly 0.7–1.5%. Rates move with the market, so we obtain live quotes from several lenders and compare fixed, variable and mixed options for you.
Non-residents should budget a 30–40% deposit plus about 10% for taxes and costs on resale homes or about 12% on new builds – so roughly 40–50% of the price for resale homes and 42–52% for new builds, available in cash. An independent lawyer is on top of that: no tariff sets the fee, the lawyer quotes it. If the new build becomes your main home, stamp duty falls from 1.4% to 0.1% and you need about 1.3 percentage points less in cash. Keep in mind that the bank applies its 60–70% to the lower of two figures, the purchase price and the valuation: if the valuation comes in below the price, your deposit grows. For resale homes above €1 million count on 11.1–11.3% instead of 10%: ITP is 11% in that band, not 9%. New builds are unaffected: VAT and stamp duty do not depend on the price. A mandatory bank valuation (tasación) costs about €300–600, and any arrangement fee is typically 0–1% of the loan.
Since Spain's 2019 mortgage law, the bank pays the notary, Land Registry and stamp duty on the mortgage deed itself – the buyer covers only the valuation and any opening fee. Lenders must also give you the binding offer (FEIN) with a mandatory 10-day reflection period before you sign at the notary.
Buildings insurance is required by any lender and sensible for every owner; lenders often also ask for life cover. SFERO arranges competitive home and life insurance as part of the financing package.
We secure the terms, you unlock your capital’s true potential.